



Retirement Income Planning

Building the nest egg is one challenge. Making it last for thirty years of retirement is another.
Retirement income planning is a crucial aspect of financial management that ensures you have a steady and reliable income stream throughout your retirement years.
As people live longer and healthier lives, the need for a well-structured retirement income plan becomes increasingly important.
By understanding the various sources of retirement income, implementing strategies to maximize your savings, and effectively managing your finances in retirement, you can achieve financial peace of mind and enjoy your golden years.
Take a look at the visual below to get a general understanding of the process for planning retirement income.

Retirement Is Not One Chapter. It Is Three.
Each phase brings its own goals, risks, and tax considerations. Understanding which phase you are in shapes how aggressively you spend, how you invest, and when you draw from each account.
1) Accumulation
Working years through age 65
Build the foundation. Maximize tax-advantaged contributions, capture employer match, and let compound growth work over decades.
- Max out 401(k) and IRA contributions
- Diversify across asset classes
- Build emergency reserves
- Consider Roth conversions in lower-income years
2) Distribution
Ages 65 to roughly 80
The active years. Travel, family, hobbies. Income flows from a coordinated mix of Social Security, portfolio withdrawals, and other sources, sequenced for tax efficiency.
- Time Social Security and pension elections
- Sequence withdrawals across account types
- Manage Roth conversions before RMDs begin
- Plan for Medicare and supplemental coverage
3) Legacy
Roughly age 80 and beyond
Simplification and transfer. Healthcare needs typically rise while discretionary spending eases. Focus shifts to legacy intent, estate efficiency, and protecting a surviving spouse.
- Long term care funding decisions
- Beneficiary review and estate planning
- Charitable strategies, QCDs from IRAs
- Trust and gifting strategies
Retirement Income Planning
Smart strategies to build, protect, and grow your retirement savings.
Start Saving Early
The earlier you start saving for retirement, the more time your money has to grow. Take advantage of compound interest by contributing to your retirement accounts as soon as possible.
Contribute to Tax-Advantaged Accounts
Utilize tax-advantaged retirement accounts such as 401(k) plans, IRAs, and Roth IRAs. These accounts offer tax benefits that can help your savings grow faster. Contributions to a traditional 401(k) or IRA are tax-deductible, while Roth IRAs offer tax-free withdrawals in retirement.
Take Advantage of Employer Contributions
Many employers offer matching contributions to their employees’ 401(k) plans. Be sure to contribute enough to take full advantage of any employer match, as this is essentially free money that can significantly boost your retirement savings.
Diversify Your Investments
A well-diversified investment portfolio can help manage risk and improve returns. Consider a mix of stocks, bonds, and other assets to create a balanced portfolio that aligns with your risk tolerance and retirement goals.
Regularly Review and Adjust Your Plan
Regularly review your retirement savings plan and make adjustments as needed. Life circumstances, market conditions, and retirement goals can change over time, so it’s important to stay flexible and adapt your strategy accordingly.
Contact Asset Strategy
Working with an Asset Strategy financial advisor can help you navigate the complexities of retirement income planning. We can provide personalized guidance and help you develop a comprehensive plan that meets your retirement goals. Set up a 15-Minute Discovery Call to discuss!
How Many Years Will $1 Million in Retirement Savings Last?
For 40 years the goal was simple: save more. Then you retire, the paychecks stop, and the question flips. Now you have to spend down the balance you spent a career building, without knowing how long it has to last. That is the part no one trains you for, and it is where a healthy-looking number can still run out too soon.
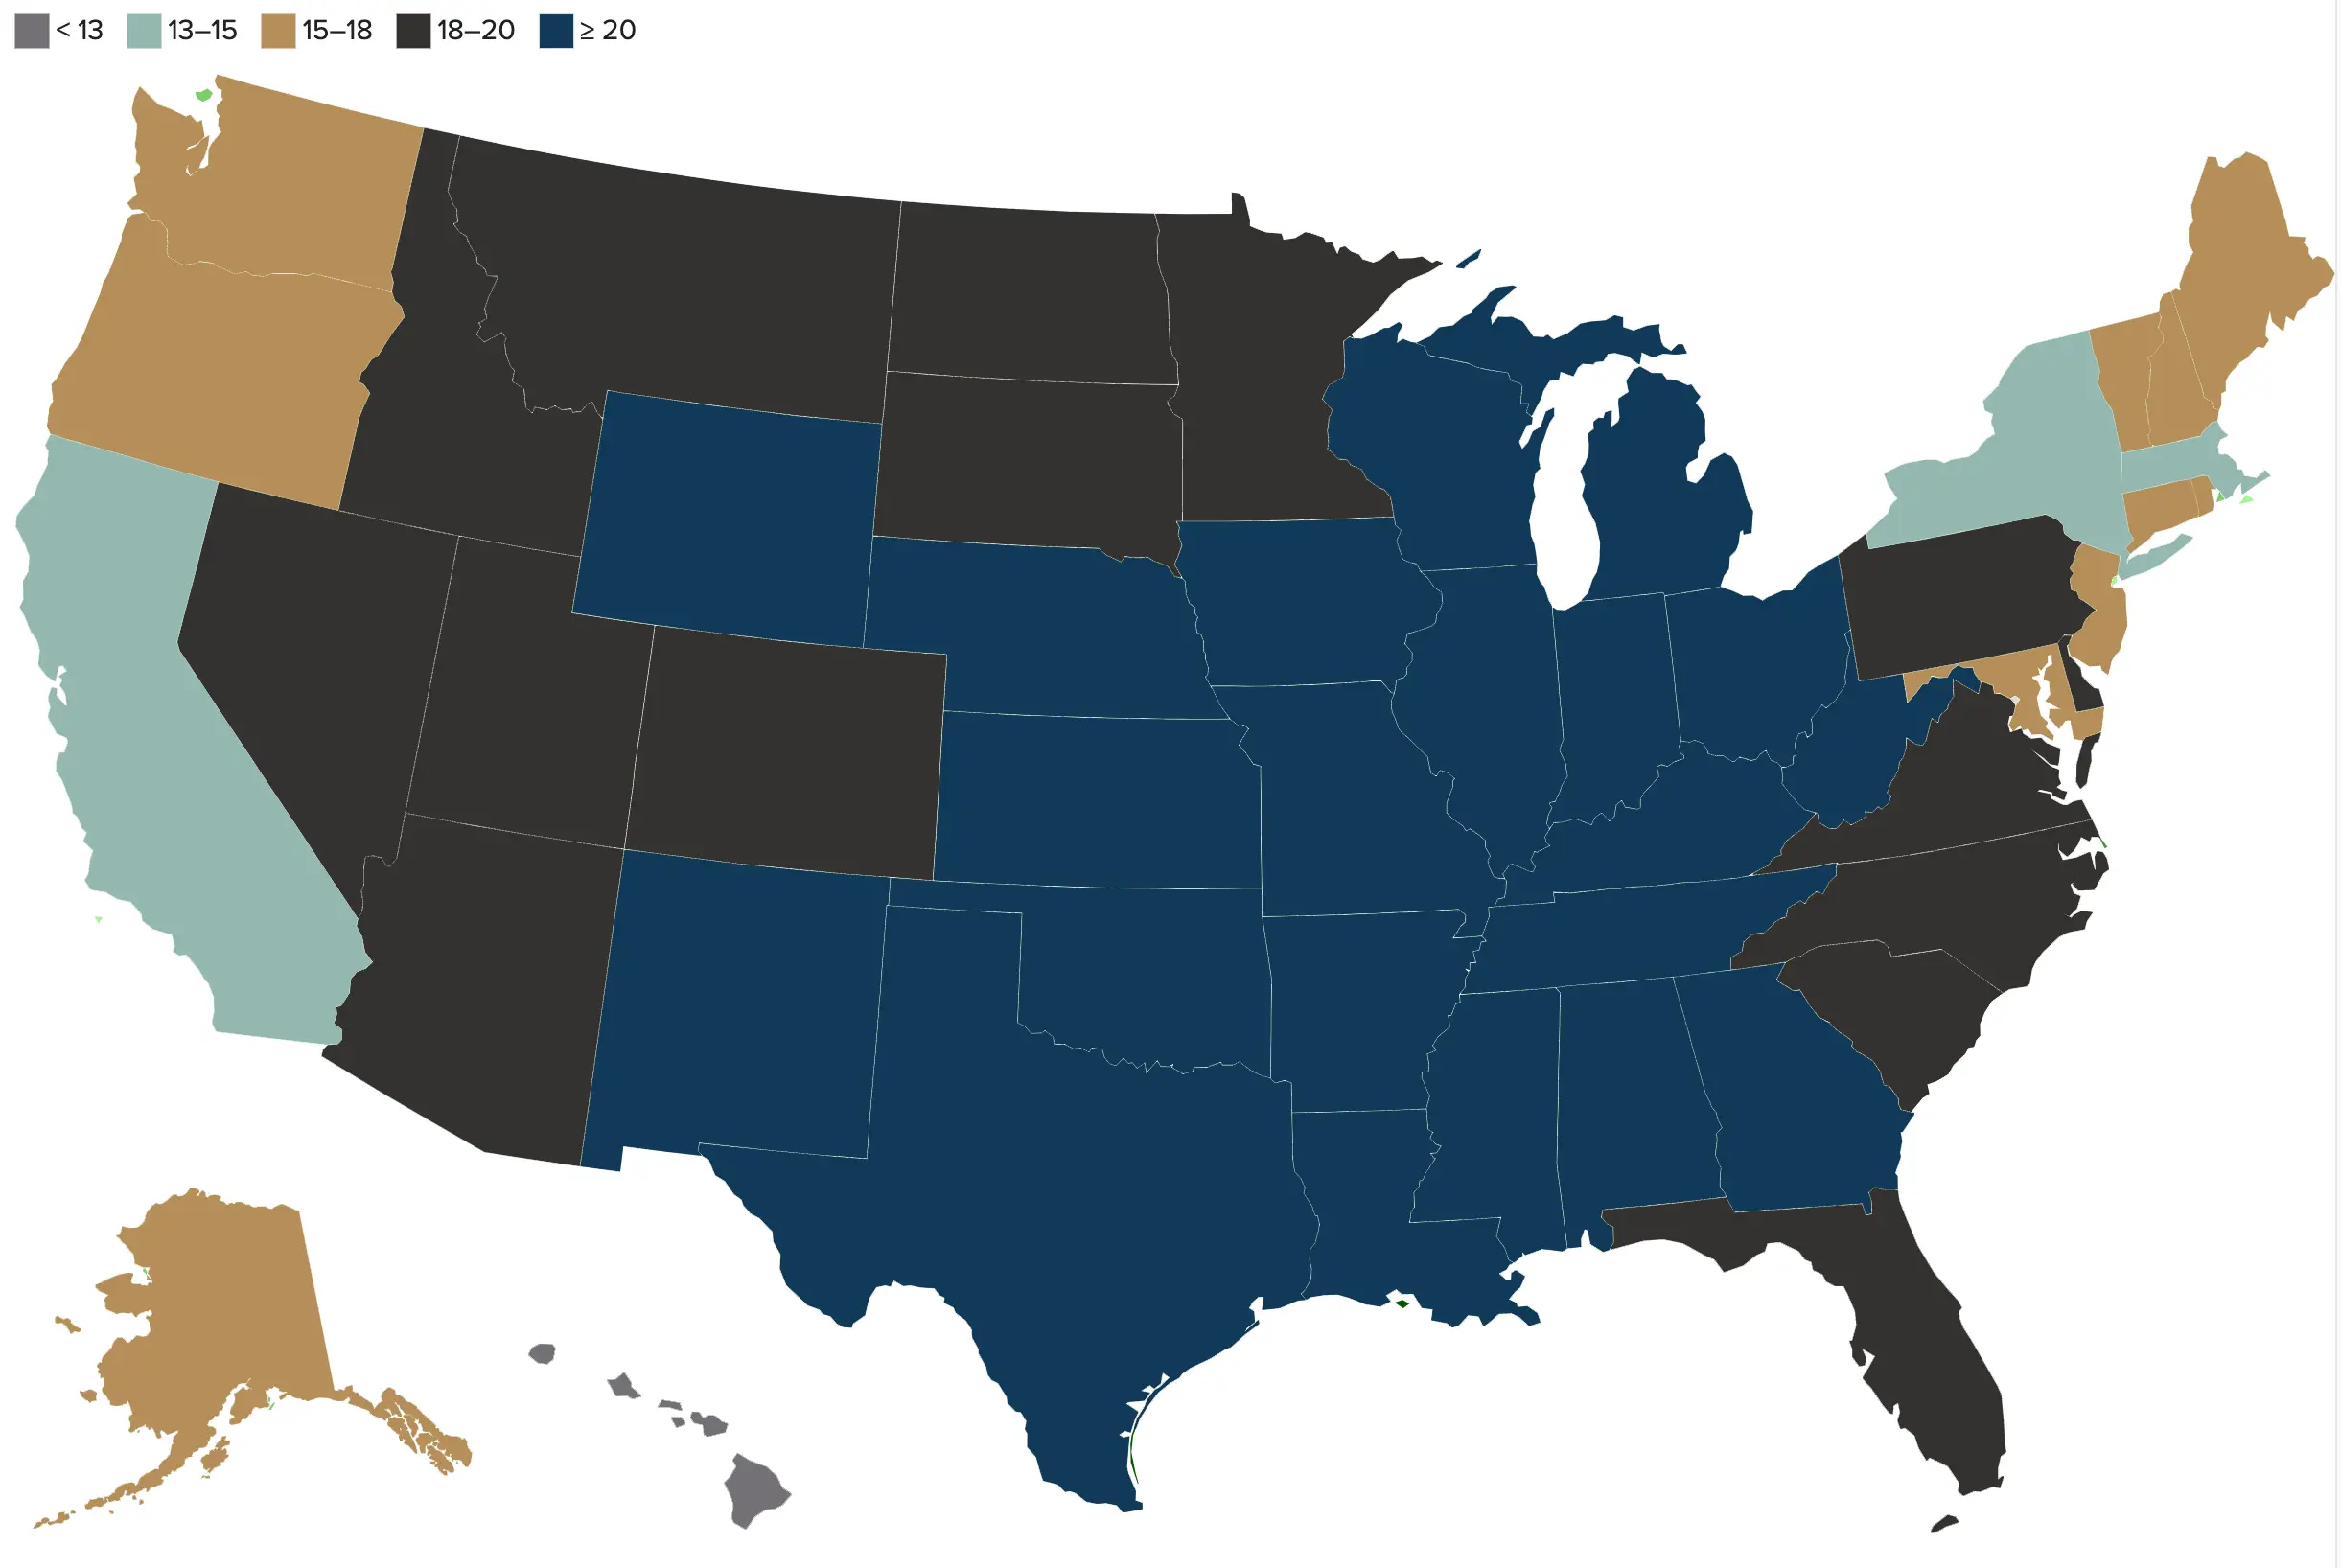
The average American needs their retirement savings to last them over a decade. But how much money is enough to live a comfortable life?
That depends on location, since living costs vary across the country. To help put things into perspective, here’s how long $1M in retirement savings would last for the average American by state.
Why Should I Choose to Work With Asset Strategy Over Anyone Else?
Already have an advisor? Many of the people we work with did too. The real question is whether anyone is coordinating your investments, taxes, Social Security, and withdrawals as one plan, or whether each sits in its own silo.
Most retirees need coordination. The accounts, the strategies, and the professionals already in their life often work in isolation, with no one responsible for the full picture. Asset Strategy was built to be that point of coordination. Here is what sets our work apart.
1)
A Truly Comprehensive Approach
2)
Specialized Expertise in Tax Strategy
3)
Independent and Fiduciary
4)
Built for Complexity
5)
A Long Term Relationship, Not a Transaction
Are You Ready to Begin?
The most valuable retirement plans are the ones built early enough to act on. Whether you are five years from retirement, recently retired, or somewhere in between, the conversation starts the same way: with a clear picture of where you are today and a candid discussion of where you want to go.
Setting up a call with us is the shortest path to clarity. There is no cost, no obligation, and no product pitch. We will listen, ask the right questions, and tell you honestly whether we are the right fit for your situation. If we are, we will outline what working together looks like.
The right time to plan is now. Time is the one resource retirement planning cannot replace, and the strategies with the most leverage, Roth conversions, Social Security timing, withdrawal sequencing, and tax aware rebalancing, all reward earlier action.
