



How Can I Get Out of Being a Landlord Tax-Efficiently?
Owning rental property once felt like a smart move. You bought at the right time, the value climbed, and the monthly checks rolled in. Nothing to complain about! But years later, your situation feels different. The property has grown into a large gain, but the thought of selling brings a wave of dread. Not because you love the work, but because you fear the tax bill waiting on the other side. What is there to do?
This is one of the most common traps real estate investors face. You want out, yet you feel stuck. The gain that makes your property valuable is the same gain that could trigger a heavy tax hit when you sell. So you hold on, year after year, and the frustration builds.
Get Out of Being a Landlord: Part I)
What Is the Real Cost of Holding On?
Let us name the part nobody puts in a fancy brochure… We call them the Terrible T’s. Every landlord knows them well. And they really are terrible.
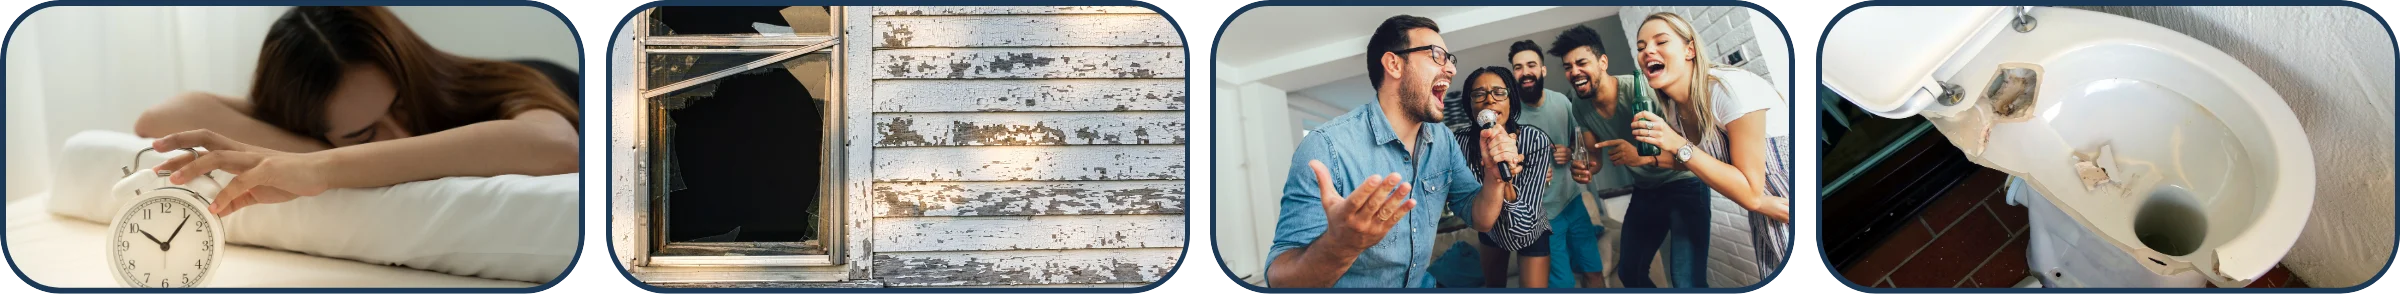
Tenants who pay late or not at all. Termites and the repairs that never seem to end. Teenagers throwing parties in your unit at 2 a.m. Toilets that flood on a holiday weekend. Add Trash, Turnover, and Taxes, and the list grows longer than the rent check.
For younger landlords, the noise is the love of the game. But for landlords who are older and ready to slow down, it wears thin. You didn’t sign up to spend your retirement answering emergency calls and chasing rent. You built this asset to support your lifestyle, not to run it into the ground!
Here is the honest truth no landlord wants to hear. The Asset Strategy team cannot fix your Terrible T’s. We will not unclog a drain or remove a bad tenant. What we can do is help you keep more of what you earned when you decide it is time to step away.
Get Out of Being a Landlord: Part II)
Why Does Selling Feel Impossible?
When you sell an appreciated rental, Uncle Sam (the government) wants his share. You may owe Federal Capital Gains Tax, State Tax, Net Investment Income Tax (NIIT), Depreciation Recapture, and in some cases Recaptured Depreciation. Stacked together, these can claim a large slice of your profit pie.
That is why so many owners freeze. Direct sales can mean handing over 30% or more of your gain.* So the property stays, the headaches continue, and the wealth stays locked in place.
The good news is that direct sales aren’t your only option. The US tax code offers several legal paths that let you exit or reposition your property while deferring, reducing, or even eliminating the tax you would otherwise owe. Each path carries its own conditions, including eligibility rules, strict timelines, minimum holding periods, and IRS requirements, and state taxes may still apply, so not every strategy fits every owner.
Get Out of Being a Landlord: Part III)
How Do You Find the Path That Fits You?
To be completely transparent with you, there is no single right answer. The best move depends on what you want your money to do next. At Asset Strategy, we start by asking a simple question. What matters most to you now?
Do You Want to Continue Growing Wealth?
If you still want your money working in real estate, but without the daily grind, certain strategies let you defer the gain and move into professionally managed property. You keep your exposure to real estate and its potential for growth, but someone else handles the Terrible T's.
Options such as a 1031 Exchange into a Delaware Statutory Trust (DST) or a Qualified Opportunity Zone (QOZ) fund may fit this goal.
Do You Want Switch to Passive Income?
Now let's say that maybe you want the monthly income without the labor. Some approaches let you trade active ownership for a passive role, so you continue receiving cash flow while stepping fully out of the landlord role.
Options such as a Delaware Statutory Trust, 721 UPREIT, Triple Net Lease property, or a third-party property management company may fit this goal.
Do You Want to Exit Real Estate Entirely?
What if you've had enough and want to be done with property altogether? There are structures that allow you to sell, spread the tax over time, and move your wealth into other investments that better match your stage of life.
Options such as an Installment Sale may fit this goal.
Do You Want to Give to Charity?
If leaving a legacy matters to you, there are charitable strategies that can turn a highly taxed asset into a gift that supports a cause you love, provides you income, and reduces your tax bill at the same time.
Options such as a Charitable Remainder Trust or a Charitable Gift Annuity may fit this goal.
Do You Want to Lower Your Risk?
For many older owners, protecting what they have beats chasing more. Certain strategies help you move from a single, concentrated property into a more diversified position, which can steady your income and calm your nerves.
Options such as a portfolio of 721 UPREITs or Qualified Opportunity Funds may fit this goal.
Get Out of Being a Landlord: Part IV)
How to Stop Being a Miserable Landlord Forever?
The belief that you are trapped is the most expensive myth in real estate.
You don’t have to choose between a brutal tax bill or a lifetime of midnight repair calls.
We are here to tell you that those are not your only two doors.
With the right plan, you can evaluate ways to honor the value you built, potentially reduce or defer taxes depending on your facts and applicable law, and work toward shaping it into something that serves the life you want next.
The key is to plan before you sell, not after. Once a sale closes, many of these options disappear. That is why the smartest step is to explore your choices early, while every path is still open.
Get Out of Being a Landlord: Part V)
Ready to Take the First Step?
You have worked harder than most building this asset. You deserve to enjoy the reward without watching a third of it vanish.
Our team helps landlords across the US design exits that fit their goals, work to protect their gains through strategies such as tax deferral planning and diversification, and finally quiet the noise. Every situation is different, and outcomes vary based on your specific facts, so results are never guaranteed.
You cannot outsource every Terrible T. But you can build a plan that lets you walk away on your own terms. Learn more and start the conversation at www.assetstrategy.com/contact.

Let’s Talk!
If you have any questions, don’t hesitate to reach out.
Asset Strategy can provide personalized advice tailored to your circumstances.
Call us at 781-235-4426, or click HERE to book a
15-Minute Discovery Call with one of our Advisors.
Advisory Services offered through Asset Strategy Advisors, LLC (ASA), a SEC Registered Investment Advisor. Securities offered through Concorde Investment Services, LLC. (CIS), member FINRA/SIPC. Insurance Services offered through Asset Strategy Financial Group, Inc. (ASFG). ASA, CIS and ASFG are separate companies.
Because investor situations and objectives vary, this information is not intended to indicate suitability for any individual investor.
Tax or legal advice should not be construed from this material. If you have questions regarding your specific situation, discuss them with your tax and legal advisors.
Sponsoring real estate investment companies, receive management fees from DST structures. While these fees are thoroughly disclosed upfront, they can have an adverse effect on cash flow levels.
DST 1031 properties are only available to Accredited Investors (typically defined as having a $1 million net worth excluding primary residence or $200,000 income individually/$300,000 jointly of the last three years; or have an active Series 7, Series 82, or Series 65. Individuals holding only a Series 66 registration may not automatically qualify; verify your status with your CPA and Attorney. If you are unsure if you are an Accredited Investor and/or an accredited entity, please verify with your CPA and Attorney.
There are material risks associated with investing in DST properties and real estate securities including liquidity, tenant vacancies, general market conditions and competition, lack of operating history, interest rate risks, the risk of new supply coming to market and softening rental rates, general risks of owning/operating commercial and multifamily properties, short term leases associated with multi-family properties, financing risks, potentially adverse tax consequences, general economic risks, development risks, long hold periods and potential loss of the entire investment principal.
Certain Qualified Opportunity Zone (QOZ) areas may not be able to appreciate as predictably as more established areas. Some neighborhoods may be more accommodating to development than others, impacting the success of the investment. Development and redevelopment of real estate traditionally have more risk than other types of real estate strategies. The availability and cost of construction and development financing is uncertain and represents a risk inherent in the execution of a QOF strategy. The rules and regulations of the QOZ Program are complex, compliance with the QOZ Program comes with significant challenges. QOFs tend to be illiquid investments for ten or more years. Any discussion regarding “Qualified Opportunity Zones”, including the viability of recycling proceeds from a sale or buyout, is based on advice received regarding the interpretation of provisions of the Tax Cut and Jobs Act of 2017 (the “Jobs Act”) and relevant guidance’s, including, among other things, two sets of proposed regulations and the final regulations issued by the IRS and Treasury Department in December of 2019. A number of unanswered questions still exist, and various uncertainties remain as to the interpretation of the Jobs Act and the rules related to Opportunity Zones investments. We cannot predict what impact, if any.
* The 30% figure is illustrative, not a promise. It reflects a higher-income seller who is married and filing jointly, whose gain is large enough to fall in the top long-term capital gains bracket. The estimate stacks federal long-term capital gains of 20% on the appreciation, depreciation recapture taxed at up to 25% on the portion tied to prior depreciation deductions, and the 3.8% net investment income tax that applies when modified adjusted gross income passes $250,000 for joint filers. It also assumes a modest state income tax, which ranges from 0% in states like Florida, Texas, and Nevada to more than 13% in California. Your actual rate depends on your income, filing status, state of residence, holding period, and depreciation history. This is general information, not tax advice. Please consult a qualified tax professional before you sell.
bd-rp-r-a-3414-7-2026
