



Strategic Tax Planning
Tax Minimization Strategies

We specialize in tax minimization strategies for Individuals & Businesses
Paying Taxes Is Required. Overpaying Isn’t.
-
Smart tax planning and tax minimization strategies aren’t about avoiding your obligations. They’re about understanding them well enough to legally minimize and optimize what you owe.
- At Asset Strategy, we offer a wide range of tax minimization strategies designed to help individuals and businesses reduce their tax burden within the boundaries of the law.
Some strategies focus on leveraging deductions to lower taxable income. Others emphasize maximizing tax credits to directly reduce liability. More advanced approaches, such as entity structuring or compensation optimization, refine key components of your financial profile to ensure greater efficiency and compliance.
Great tax planning is about being intentional, proactive, and informed.
How Is Tax Planning Different from Tax Preparation?
Tax planning refers to our review of your tax return to identify potential planning opportunities (both now and in the future) to keep your lifetime tax liability as low as possible.
This is different than tax preparation (usually done by your CPA, EA, or an online service like TurboTax), which is focused on keeping you compliant with what the government thinks you owe each year.
What’s the Most Expensive Tax Planning Mistake?
Not Knowing What You’re Missing.
Every April you sign the return, pay what it says, and move on. The number looks official, so you assume it is as low as it can go. It rarely is. Most strategies that lower it have to be in place months earlier, and by filing season the window has closed. What you overpay does not come back.
Effective tax planning is about more than minimizing your liability. It’s about uncovering smart, legal tax minimization strategies you may not even know exist.
During your tax planning process, we’ll explore a range of opportunities tailored to your unique financial picture. This may include evaluating the most tax-efficient retirement vehicles, optimizing charitable giving, strategically realizing capital gains, assessing eligibility for tax credits, and considering Roth IRA conversions.
We can also model the impact of key financial events, such as changes in filing status, the addition of dependents, stock option exercises, or the sale of a business, to help you understand how they might affect your upcoming tax liability.
The earlier you plan, the more flexibility and clarity you have.
"Anyone may arrange his affairs so that his taxes shall be as low as possible; he is not bound to choose that pattern which best pays the treasury. There is not even a patriotic duty to increase one's taxes. Over and over again the Courts have said that there is nothing sinister in so arranging affairs as to keep taxes as low as possible. Everyone does it, rich and poor alike and all do right, for nobody owes any public duty to pay more than the law demands."
 I.R.C. § 1031Large Capital Gain
Delaware Statutory Trust (DST) 1031 Exchange
View strategy I.R.C. § 1400Z-2Large Capital Gain
Qualified Opportunity Funds/Zones (QOF/QOZ)
View strategy I.R.C. § 1259Large Capital Gain
Concentrated Stock / Constructive Sale Rule
View strategy I.R.C. § 351Large Capital Gain
351 Transfer
View strategy



 I.R.C. § 170(a), 170(c)Charitable Giving
Gifting Strategies (CRT)
View strategy I.R.C. § 170, 4966Charitable Giving
Donor-Advised Fund (DAF)
View strategy I.R.C. § 170(e)Charitable Giving
Gifts of Securities or Real Estate
View strategy I.R.C. § 501(c)(3), 509(a)Charitable Giving
Private Family Foundation
View strategy I.R.C. § 408(d)(8)Charitable Giving
QCDs from IRAs
View strategy I.R.C. § 63, 170Charitable Giving
Bunching / Charitable Clumping
View strategy I.R.C. § 170, 7702Charitable Giving
Charitable Planning with Life Insurance
View strategy I.R.C. § 170(h)Charitable Giving
Land Conservation
View strategy

You Can’t Optimize What You Don’t Plan
Taxes touch nearly every part of your financial life. And your tax return? It’s not just paperwork, it’s a unique, detailed snapshot of your financial identity, filled with valuable clues that are often hidden within dozens of pages and hundreds of numbers.
When we take the time to thoroughly understand your return, we’re better equipped to engage in smarter, more strategic conversations that lead to real, actionable outcomes.
At Asset Strategy, we help demystify the complex world of income taxes. By translating technical tax data into insights you can actually use, we give you the clarity and confidence to make informed financial decisions.
Is Tax Planning Overrated?
That’s Exactly Why You Might Be Overpaying.
Regardless of income sources or filing status, nearly anyone who pays income taxes can benefit from having a professional review of their tax return to identify relevant planning opportunities. At worst, we’ll review your return and conclude you are currently maximizing every available tax-saving opportunity. That’s great “peace of mind” news. Alternatively, and more frequently, we’ll identify a handful of tax-saving opportunities, both in the current year and in future years.
Year-Round Tax Strategy
Tax Planning Follows the Seasons
A skilled advisor revisits your tax picture through every season of the year, adjusting the plan as your income, deadlines, and goals shift.
Asset Strategy coordinates these steps alongside your tax professional throughout the year.
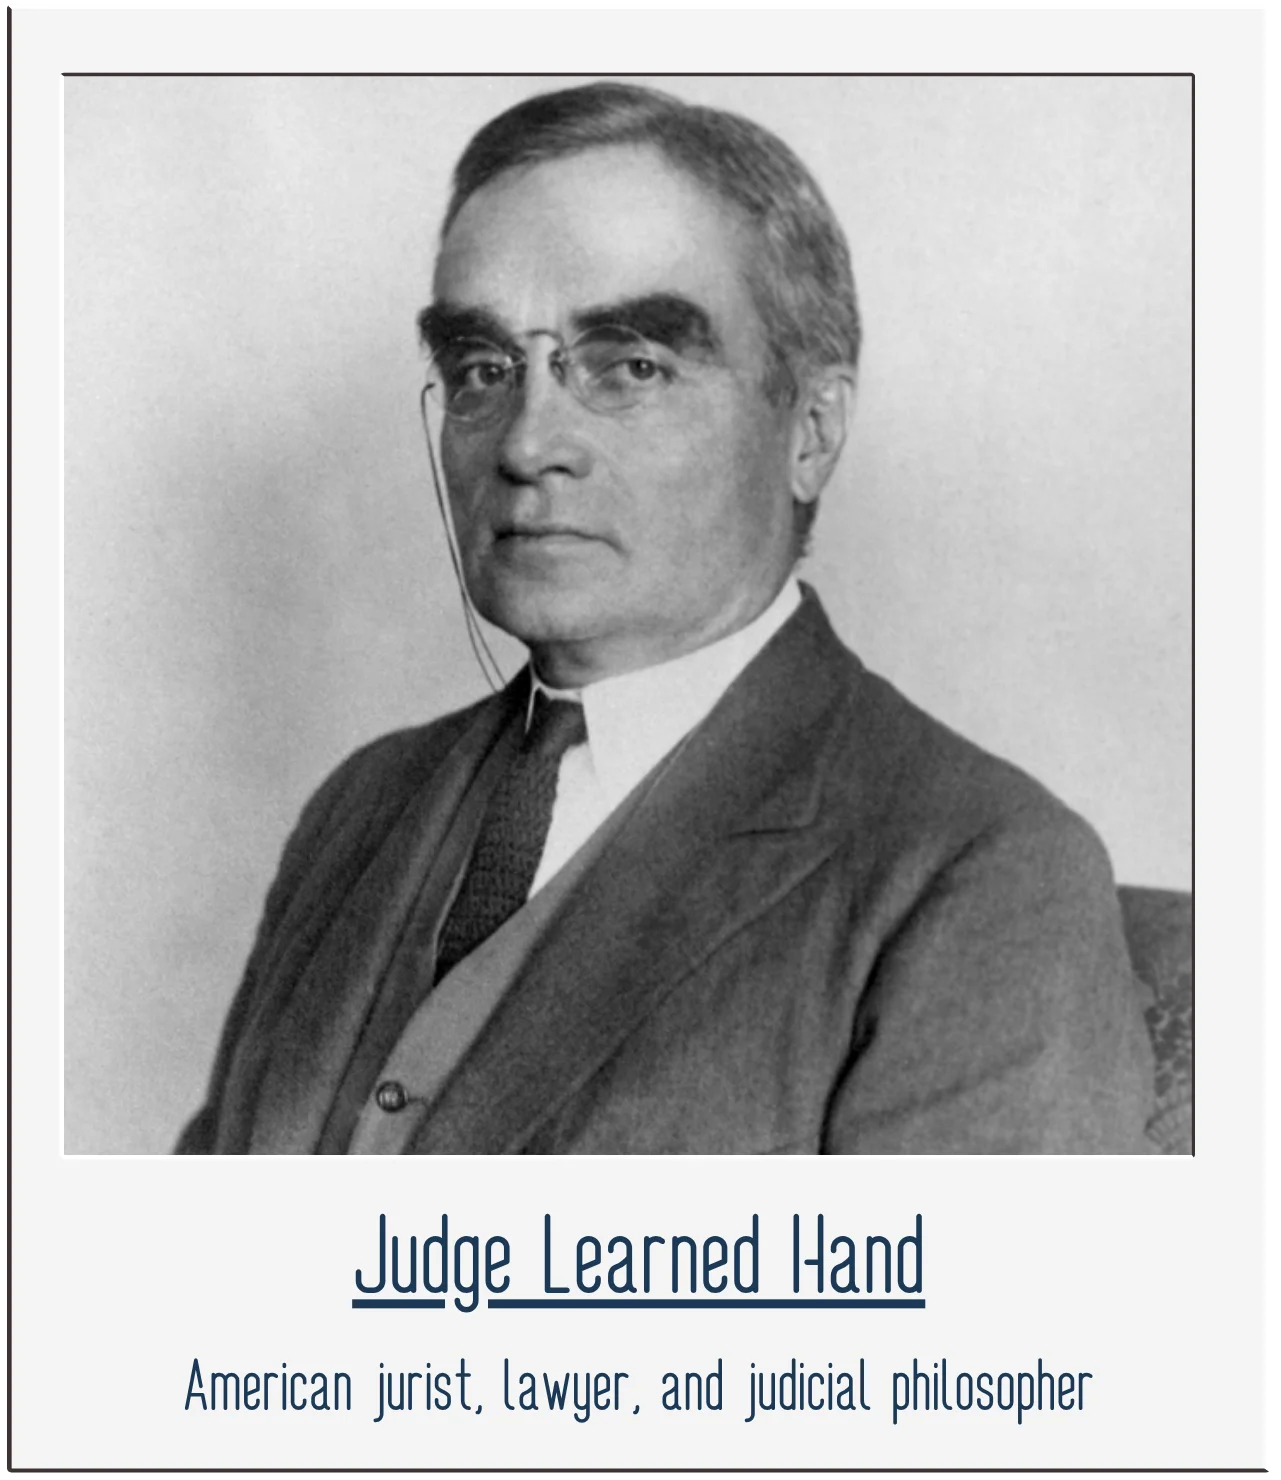
“In America, there are two tax systems: one for the informed and one for the uninformed. Both are legal.”
-Judge Learned Hand
Meaning: The tax code offers many legal ways to manage what you owe, but they tend to benefit people who know about them and plan ahead.
Before Speaking With Us, Here Are Some Common Questions About Tax Planning
At what income or asset level does Tax Planning start to pay off?
There is no single threshold, because what drives the value is complexity, not just income. Tax Planning tends to pay off once you have multiple income sources, business ownership, equity compensation, real estate, or a major liquidity event on the horizon, since those are the situations where small decisions carry large tax consequences. A straightforward W-2 return has fewer levers, but even then a one-time review can confirm you are not leaving anything on the table!
How much money will a tax strategist save me?
Your savings depend entirely on your situation, so any firm promising a fixed number before reviewing your return is guessing. Honest Tax Planning starts by examining what you file, then quantifies specific opportunities such as retirement vehicle selection, gain timing, or entity structure that apply to you. In some cases you may already be optimized and the value is confirmation, while in many others the identified savings span both the current year and years to come.
Why do people so often wait too long to start Tax Planning?
Most people treat taxes as a once-a-year filing task, so they reach out in spring when the year they are filing for is already closed. The hard truth is that by then the highest-value Tax Planning moves are off the table because they had to happen during the tax year itself. Starting earlier is the difference between shaping your liability and simply reporting it.
Should I bring in Tax Planning help before or during tax season?
Before, and ideally well before. Most of the meaningful moves, such as gain harvesting, Roth conversions, charitable timing, and entity decisions, have to happen during the tax year, not after it closes, so by filing season your options have largely narrowed to reporting what already occurred. Effective Tax Planning lives in the months before the deadline, where you still have time to act.
Should I get Tax Planning help when I have a major life change?
Yes, and the best time is before the change is final, not after. Events such as selling a business, exercising stock options, marrying, having a child, receiving an inheritance, or retiring can each reshape your tax picture, and Tax Planning lets you model the impact before it lands on a return. Acting early often opens timing and structuring choices that disappear once the event is complete.
How often should I meet with my tax planner?
At least once a year for a full review, with additional check-ins whenever your circumstances shift. Tax Planning works best as an ongoing relationship rather than a single appointment, because the law changes, your income changes, and the right move in one year may be the wrong one the next. A mid-year conversation often matters more than a year-end one, since it leaves time to act before December 31.
Which tax minimization strategies should a strong tax plan include?
A strong plan starts with a close read of your return and extends well beyond a single filing year. Good Tax Planning should address the timing of income and capital gains, the most efficient retirement and charitable vehicles for you, coordination across your investment and estate decisions, and a clear view of how upcoming life events will affect future liability. The goal is a multi-year roadmap, not a once-a-year scramble.
Let’s Find What You’re Missing
Here is what a review looks like. We read your latest return line by line, model the events coming up in your life, and map the tax minimization strategies that fit. If you are already capturing everything available, we will tell you. More often, we find opportunities worth acting on this year and beyond. As fiduciaries, our only job in that room is your interest. Schedule your tax review today.
