



Insurance / Protection

The Fourth Pillar of Financial Wellness.
For Individuals, Families, and Businesses.

1) Emergency Savings Account
2) Budget
3) Debt
4) Insurance / Protection
5) Investment / Retirement
“A policy of life insurance is the cheapest and safest mode of making a certain provision for one’s family.”
– Benjamin Franklin
For a quick and easy quote for life or long-term care insurance customized to your unique situation, follow the buttons below.
Asset Strategy offers several products that require more specialized servicing by our experienced professionals.
Below you will find a number of additional resources to help you better understand some of the options.
Asset Strategy covers:
Life Insurance
Annuities
Long-Term Care (LTC)
Disability
Life Insurance
An insurer’s guarantee to pay an insured’s beneficiaries after death in exchange for a premium.
Annuities
Contracts with a life insurance provider for periodic payouts for retirement planning.
LTC
Services for long-term illness or disability patients who can’t care for themselves.
Disability
Financial coverage for missed income if illness/injury prevents work.
Protection and Insurance go hand in hand, working in tandem to help shield individuals, families, and businesses from unforeseen risks and uncertainties. At their core, both concepts revolve around the fundamental principle of mitigating potential losses and providing peace of mind.
Why Insurance is Important
Protection encompasses a proactive approach to risk management, involving measures such as prudent financial planning, emergency savings, and risk avoidance strategies.
Insurance serves as a safety net, offering financial compensation in the event of accidents, illnesses, property damage, or other covered perils. Whether it’s health insurance safeguarding against medical expenses, auto insurance covering vehicle repairs, or life insurance providing for loved ones in the event of untimely demise, insurance policies provide a layer of financial protection that complements individual efforts.
Life Insurance
Most of us need 5-10 times our income plus an additional $100K/ dependent child. If you are the major bread winner in the family and you carry a significant debt load, aim toward the high end of the recommended range.
Disability
Evaluate your risk of disability and consider insuring against this risk.
Long-Term Care
Start the evaluation of this coverage at mid-life, not late in life when it will be too expensive. Consider leveraging hybrid coverage where LTC or critical illness coverage is part of a life insurance foundation.
Property / Casualty
Maintain adequate levels of protection, including Personal Umbrella coverage. Use higher deductible limits (Self-insured retention) to keep costs down.
Health Coverage
Consider a High Deductible Health Plan (HDHP) in combination with funding your HSA, and let the HSA build up.
- 2026 Family limit: $8,750, Self-only: $4,400
- (+ $1,000 catch-up)
Wills / Trusts
Part of Foundational Financial Planning includes making sure your affairs are in order. Basic Wills, Durable Powers, Healthcare proxies, or the use of Trusts must be in place and regularly reviewed to reflect life changes.
2026
Long-Term Care
Introduction
2026
Health Savings Accounts
The Guide
2026
Life Settlements
Brief Overview
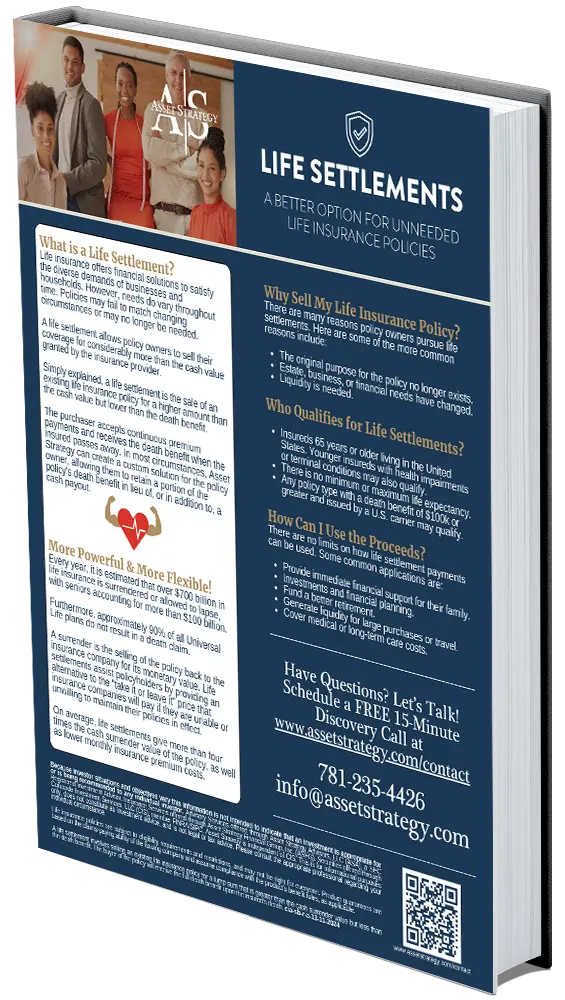
2026
Life Insurance
The Basics
Did You Know? Click on the images below to expand.
Source: Forbes


